Steinvar SaveTerm deposits and savingsDeposit products defined in an afternoon.
A deposit product in Steinvar is a declaration, not a project: its rates, tiers, day count, compounding, payout, tax and early-withdrawal terms are data. The night run accrues and pays interest exactly once, and every agreement is signed before money moves.
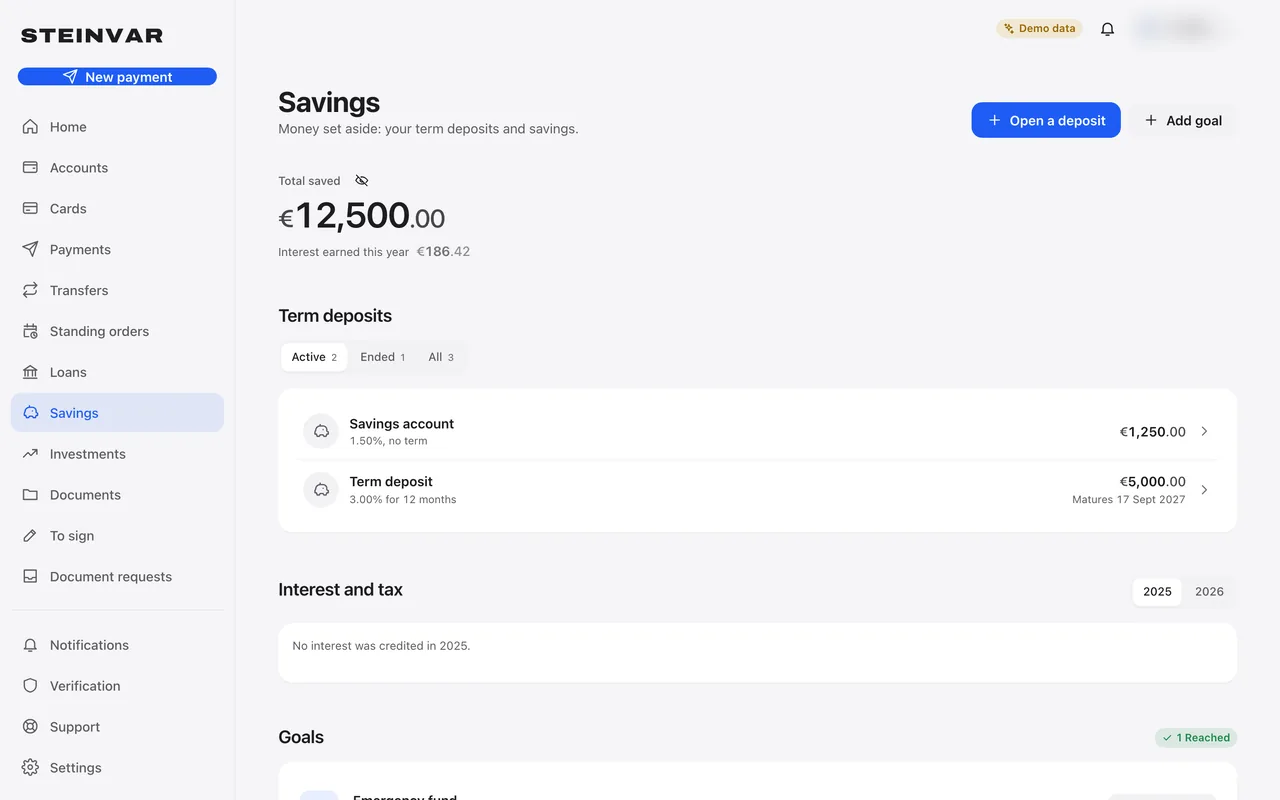
Customer e-banking, from its demo bank; names are blurred.
- 5
- day-count conventions, from ACT/360 to 30E/360
- Nightly
- accrual, posted exactly once with catch-up
- Signed
- agreement before the deposit is funded
Products
Term deposits and savings
Fixed-term deposits and open-ended savings from the same engine, each product a template with its own terms.
Rates
Fixed, tiered by balance, or floating on a reference rate with a floor. Reference rates are entered under four-eyes.
Conventions
ACT/360, ACT/365F, ACT/ACT-ISDA, 30/360 and 30E/360; compounding and rounding modes per product; civil dates, so a clock change never moves a day.
Payout
At maturity, monthly or capitalised, with renewal at maturity and business-day holidays per workplace.
Lifecycle
Opening
Opened in the back office or by the customer in e-banking, behind the verification gate; the agreement is signed in Docs before funding.
Funding once
A funding claim and a unique journal entry mean a deposit is funded once, however often the request arrives.
Top-ups and withdrawals
Partial or full early withdrawal, with a fee or a fallback rate, and interest already paid clawed back pro rata with its tax.
The night run
Accrual, settlement, maturity and rollover each night, with stale-run takeover and catch-up for missed days.
Tax
Withholding
Tax withheld on each payout at the product’s rate and posted to the tax-payable account.
Remittance
Each month’s tax per currency is proposed by one employee and approved by another, booked against the account it is paid from.
The return
Interest and tax per payee with personal codes and residence, downloadable for the monthly and yearly tax filings.
How a deposit runs
Offer
The customer or an employee picks a product and term; the quote shows the rate and interest.
Agreement
The agreement is generated and signed in Docs.
Funding
Money moves from the current account to the deposit, once.
Nights
Interest accrues each night and is paid or capitalised on its dates, tax withheld.
Maturity
The deposit renews or pays out, and the customer is told.
Controls built in.
Four-eyes changes
Withdrawals and renewal changes raised in the back office, tax remittances and reference rates each need a second employee.
Frozen terms
A deposit keeps the product terms it was opened on; a new product version changes new deposits only.
Uncertain outcomes held
A posting whose outcome is unknown is held for a person to resolve, never retried blindly.
Standards and formats
- ACT/360
- ACT/365F
- ACT/ACT-ISDA
- 30/360
- 30E/360
- Withholding tax
Not in this module today
- The deposit-guarantee single customer view is on the roadmap.
- Withholding is a flat rate per product; exemptions by the client’s residence are not applied automatically.
Questions about Steinvar Save
Can a customer open a deposit in e-banking?
Yes, from the products your bank offers there, after verification. The agreement is signed in e-banking before the deposit is funded.
What happens on early withdrawal?
The product decides: a fee, a lower fallback rate, or not allowed. Interest already paid above the entitlement is clawed back with its tax.